


For most of their history, stablecoins have lived inside crypto. They move between exchanges, sit in DeFi protocols, provide collateral and give traders a way to hold dollars without leaving onchain markets.
Ethena has become one of the biggest examples of how far that model can scale. Since USDe launched in 2024, more than $30 billion has moved through its mint and redeem system, over $750 million in rewards have been distributed across the Ethena ecosystem, and USDe has found its way into more than 100 venues and protocols.
Ethena Pay takes that infrastructure somewhere different.
The new consumer app is built exclusively on Avalanche and packages USDe into an experience designed around three familiar actions: save, send and spend. Users can hold a self custodial dollar balance, move money globally, connect to fiat banking rails through a virtual IBAN and spend through a card, while much of the blockchain complexity stays underneath the interface.
That makes the launch interesting for reasons that go beyond another stablecoin payment product. Ethena is trying to move from serving primarily traders, institutions and existing onchain users toward building a direct consumer relationship around USDe. Its decision to build that experience on Avalanche also gives us a useful look at what blockchain adoption may look like when the technology becomes infrastructure rather than the product people think about.
From digital dollar to consumer product
USDe already had distribution before Ethena Pay.
It is integrated across more than 100 venues and protocols, giving users access through exchanges, DeFi applications and other financial platforms. That helped Ethena scale quickly, but it also meant the consumer relationship largely belonged to somebody else. The exchange controlled the interface. The lending protocol controlled how USDe was presented. Ethena provided the asset underneath.
Ethena Pay changes that relationship.
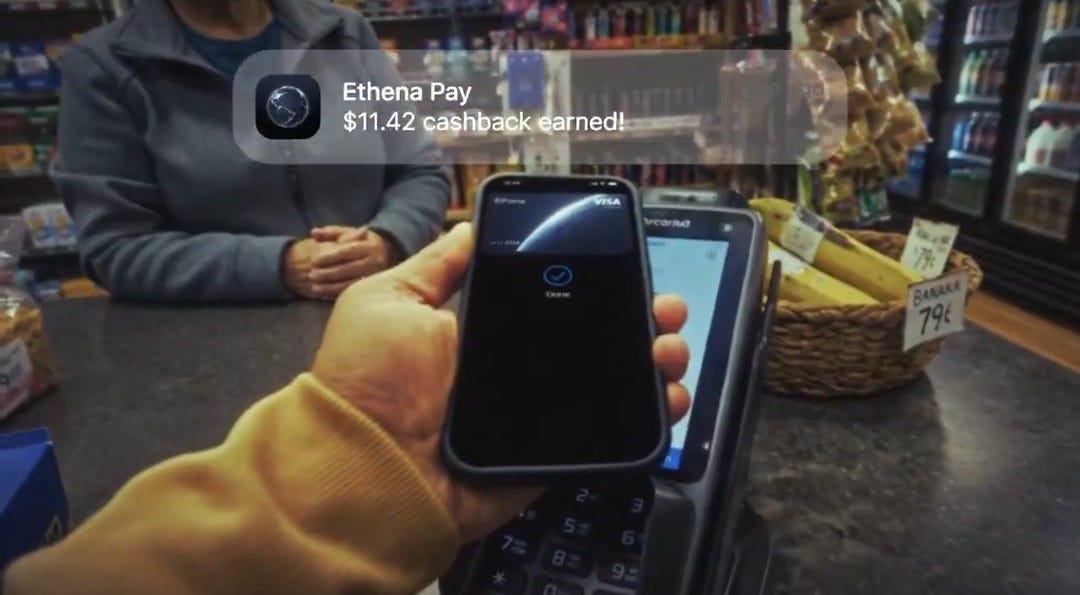
Inside the app, incoming holdings are converted into USDe and the same underlying asset can support balances, transfers and spending. Users can send money to other Ethena Pay users at no cost, withdraw to external wallets or bank accounts, access a virtual IBAN and use a payment card from the same interface. Ethena Pay also offers daily rewards on eligible balances and cashback on qualifying card purchases, with the exact rates and limits varying by user tier.
More importantly, Ethena now owns the distribution layer.
That matters because consumer money behaves differently from capital moving around DeFi in search of opportunities. Salaries arrive regularly. People keep balances available for bills and purchases. Payment accounts become part of everyday routines. If Ethena can move even part of USDe demand in that direction, it could create a different type of user base around the asset.
Guy Young, founder of Ethena, described the opportunity during a recent Layer One conversation in terms of the much larger market around saving and moving money. His point was straightforward: financial activity extends far beyond trading, and products built around savings, payments and credit can reach people who may have little interest in becoming active crypto users.
That brings us to the infrastructure underneath Ethena Pay.
Why Avalanche?
Ethena Pay is using Avalanche as the exclusive settlement layer for its product suite.
For a consumer financial application, the blockchain has to disappear into the experience. Transfers need to settle quickly. Costs need to remain low enough for frequent transactions. The infrastructure also has to support a product that could eventually serve users across many markets without forcing them to understand wallets, bridges or network mechanics.
Ethena says Avalanche provides the fast finality, low costs and flexible infrastructure required for money movement, payments and settlement across Ethena Pay. The product currently runs on Avalanche C-Chain, giving Ethena access to an established EVM environment while keeping open the possibility of more dedicated infrastructure if its requirements change as the product scales.
The choice is particularly interesting because Ethena could have pursued its own blockchain.
During the Layer One conversation, Young discussed why that was unnecessary for what Ethena is trying to accomplish. Building another chain would introduce an additional technical environment when the company’s priority is getting its financial products in front of users. Avalanche gives Ethena somewhere to deploy today, with C-Chain providing shared infrastructure and Avalanche’s broader architecture leaving room for an application specific L1 later if the product eventually requires dedicated blockspace or greater customization.
That approach keeps the focus on the application.
Ethena does not need consumers to care which chain processes a payment. It needs the payment to work.
Invisible adoption
John Nahas described Avalanche’s role in Ethena Pay with a simple phrase during the same conversation: “invisible adoption at scale.”
That may be the most important idea behind the entire launch.
A large part of crypto adoption has historically required users to become crypto users first. They learn about networks, wallets, gas, bridges, seed phrases and token standards before reaching the financial service they actually wanted.
Ethena Pay is approaching the experience from the opposite direction. A person can sign in using familiar account methods, secure access with passkeys and biometrics, hold a dollar balance, transfer money and spend from an app that looks much closer to modern fintech than a typical crypto wallet. The wallet underneath remains self custodial, while the technical complexity is pushed away from the main experience.
Avalanche benefits from that model precisely because the network does not have to become the consumer brand.
If millions of payments, transfers and financial interactions eventually happen through applications where users rarely think about the blockchain processing them, adoption starts looking less like convincing people to use crypto and more like businesses choosing blockchain infrastructure because it makes their products better.
That is a very different path to scale.
Where stablecoins go from here
Ethena Pay launched across 48 supported countries, with additional markets planned as regulatory and product requirements are completed. Its current availability already stretches across Latin America, the Caribbean, Africa, Asia, the Middle East and Oceania.
The geographic reach matters, but the larger experiment is what happens inside the product.
Stablecoins have already proven that digital dollars can move globally on open networks. Ethena Pay is testing whether those same rails can sit underneath the financial activities people perform every day.
That could eventually go beyond payments.
Ethena has already discussed connecting more DeFi functionality to the app while keeping the complexity away from consumers. Its launch materials describe plans for one click access to strategies built using existing USDe integrations, while the Layer One conversation touched on a broader embedded finance opportunity where onchain liquidity, yield and tokenized financial products can become components inside consumer applications.
This is where Avalanche’s growing financial ecosystem becomes relevant beyond transaction performance alone. An application like Ethena Pay can potentially sit above stablecoins, DeFi liquidity and tokenized assets, turning infrastructure that currently serves mostly onchain participants into financial products built for a much wider audience.
The user does not need to interact with each layer separately. The application can do that work underneath.
The bigger picture
Ethena Pay is still early. Availability remains limited by jurisdiction, several planned features are still rolling out, and its consumer ambitions will ultimately be judged by whether people actually choose to use the product at scale. Ethena Pay itself is also clear that it is a non custodial money app rather than a bank, with fiat services provided through third party financial partners.
But the model is worth paying attention to.
Ethena spent its first phase proving that USDe could find significant demand across crypto markets. With Ethena Pay, it is trying to turn that digital dollar infrastructure into something people can use as part of everyday financial life.
Avalanche’s role is equally revealing. It was chosen to operate underneath that experience as the exclusive settlement layer, processing the activity while much of the blockchain itself stays out of sight.
If this model works, the next wave of onchain users may never think of themselves as onchain users at all.
They may simply open an app, save money, send it somewhere and pay for something.
Avalanche will be working underneath.
Dive into the Avalanche ecosystem today! Download the Core Wallet and unlock a world of seamless DeFi, NFTs, and more.

Great